Key Takeaways
- No formula sets a car accident settlement. Adjusters weigh injury severity, proof of fault, documented losses, and available insurance together.
- Some facts tend to strengthen a claim (consistent treatment, clear liability evidence, solid wage records); others tend to weaken it (gaps in care, disputed fault, low policy limits).
- The number on an offer letter is not the amount a person keeps. Liens, unpaid bills, fees, and costs come out of the gross figure.
- Signing a release usually ends the claim for good, so timing matters as much as the dollar amount.
Two collisions with similar vehicle damage can lead to very different settlement conversations. One driver feels sore for a week and recovers fully. Another needs months of physical therapy, misses work, and still has trouble lifting a child. Insurers know this, which is why they evaluate the facts behind a claim rather than the photos of the bumper.
This article looks at the factors that most often push a settlement offer up or down, so that anyone holding an offer can ask better questions about it.
Why Online Averages Mislead
Published “average settlement” figures mix together minor soft-tissue claims and catastrophic injuries, cases with clear liability and cases with shared fault, and drivers carrying minimum limits alongside drivers with large umbrella policies. An average built from that mix says very little about a single claim. A better starting point is to look at the specific facts an adjuster will examine.
Factors That Tend to Increase Claim Value
Injury Severity and Lasting Effects
Fractures, surgery, injections, and conditions that leave permanent limitations generally carry more weight than injuries that resolve quickly. Duration matters as much as diagnosis: a sprain that still limits movement a year later can be more significant than a fracture that healed cleanly.
Consistent, Well-Documented Treatment
Medical records connect the crash to the injury. Emergency notes, imaging, therapy records, specialist visits, prescriptions, and written work restrictions show what happened and what care was needed. A clear diagnosis and treatment history tells a more complete story than a stack of bills.
Treatment decisions should always be based on health needs. More care does not automatically mean more value; care matters when it is medically appropriate and tied to the injuries in the claim.
Clear Evidence of Fault
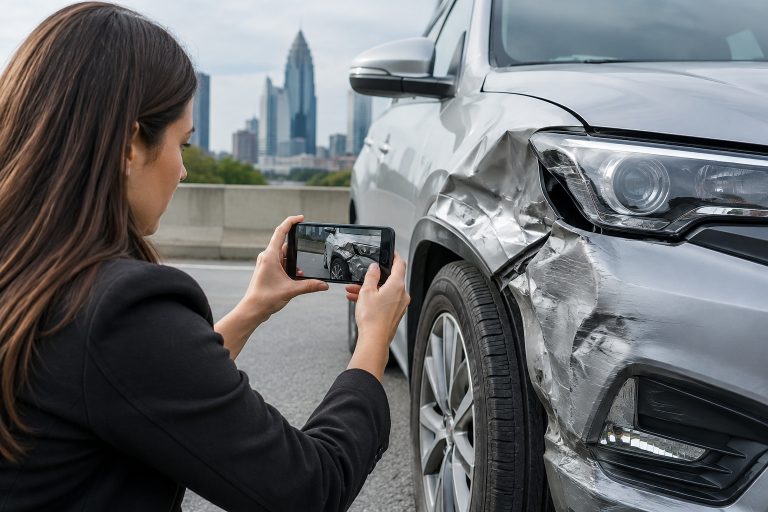
When liability is easy to establish, there is less room to argue about who should pay. Photographs of the vehicles and roadway, witness contact information, the crash report, dashcam or surveillance video, and a written timeline all help. The NAIC’s consumer guidance on filing an auto claim lists the basic information worth collecting after a collision.
Well-Supported Financial Losses
Adjusters look for proof. Losses that are documented with records are much easier to credit than estimates. Common categories include:
- Past medical costs: emergency care, appointments, testing, therapy, and prescriptions.
- Future medical needs: continued rehabilitation, procedures, or equipment that a provider has recommended in writing.
- Lost income: missed shifts, unpaid leave, reduced hours, or lost business income.
- Reduced earning capacity: long-term work limitations caused by the injury.
- Out-of-pocket expenses: mileage to appointments, medical supplies, and paid help at home.
Factors That Tend to Reduce Claim Value
Shared Fault
Many states use comparative fault rules, which reduce recovery by the injured person’s share of responsibility.[1] Some states bar recovery once that share reaches a set threshold, and a few still apply stricter rules. Because the approach differs from state to state, the location of the crash matters. Statements made at the scene or to an adjuster can also be used in the fault analysis, so it is better to describe known facts than to guess or apologize.
Gaps in Care or Inconsistent Records
A long gap between the crash and the first appointment, or between appointments, does not automatically defeat a claim. It can, however, give an insurer room to argue that symptoms came from something else or resolved earlier. If care was delayed because of cost, scheduling, or transportation, that reason should be documented.
Low Insurance Limits
A claim can be well documented and still be limited by the coverage available. Bodily injury liability coverage applies when an insured driver is legally responsible for someone else’s injuries, but it pays only up to the policy limit. Uninsured and underinsured motorist coverage on the injured person’s own policy may fill part of the gap. The NAIC’s overview of auto insurance explains the differences among liability, uninsured motorist, underinsured motorist, medical payments, and other coverages.[2] Declarations pages show the actual limits; guessing at them is a common mistake.
Minor-Looking Vehicle Damage
Insurers sometimes point to light vehicle damage to argue that an injury must be minor. Research on low-speed collisions has questioned how closely vehicle damage tracks injury risk, so property damage alone is not a reliable measure.[3] Consistent medical findings are more persuasive than photos of a bumper, in either direction.
Using a Calculator Without Over-Relying on It
Before responding to an offer, it can help to organize the numbers in one place. A car accident settlement calculator can walk through treatment, lost wages, injury severity, fault, and coverage to produce an informational range. It cannot weigh the credibility of a witness, read a policy, or predict how a specific insurer will respond, so its result is a planning aid, not a valuation.
Reading an Early Settlement Offer
Before accepting an early offer, ask a few practical questions:
- Is the medical picture clear yet, or is treatment still ongoing?
- Does the offer account for future care that a provider has recommended?
- Have all wage losses been documented and included?
- Does the offer require a full release of all claims from the incident?
- What will remain after medical liens, unpaid bills, health insurance reimbursement, fees, and costs?
The written terms matter as much as the gross figure. A release signed too early may prevent any further recovery for the same crash, even if symptoms later get worse.
Common Mistakes That Can Lower a Settlement
- Accepting an offer before the medical outlook is reasonably clear.
- Discarding photos, receipts, pay stubs, or reports.
- Posting about the crash or recovery on social media, where comments can be taken out of context.
- Speculating about fault instead of describing what is known.
- Skipping follow-up care without recording the reason.
- Overlooking uninsured or underinsured motorist coverage on one’s own policy.
- Missing the filing deadline. Statutes of limitations vary by state and can bar a claim entirely.
Frequently Asked Questions
What is the single most important factor?
There usually is not one. Injury severity often drives the size of a claim, but liability evidence and available insurance can set practical limits regardless of how serious the injury is.
Can a small crash lead to a significant injury claim?
It can. Vehicle damage is only one piece of evidence. Medical findings and consistent records say more about an injury than the appearance of the car.
Does more medical treatment always mean a higher settlement?
No. Treatment carries weight when it is reasonable, documented, and connected to the crash.
When should someone talk to a lawyer?
Legal advice is worth considering when injuries are serious, fault is disputed, coverage is unclear, or a release arrives before treatment is complete. Rules differ by state, and this article is general information rather than legal advice.
Conclusion
Settlement value reflects the whole record: how badly someone was hurt and for how long, how clearly fault can be shown, how well losses are documented, and how much insurance is available. Understanding which facts help and which hurt makes it easier to judge whether an offer reflects the claim.
References
- Legal Information Institute, Cornell Law School. “Comparative Negligence.” Wex Legal Dictionary. https://www.law.cornell.edu/wex/comparative_negligence
- National Association of Insurance Commissioners (NAIC). A Consumer’s Guide to Auto Insurance. 2022. https://content.naic.org/sites/default/files/publication-aut-pp-consumer-auto.pdf
- Croft AC, Freeman MD. Correlating crash severity with injury risk, injury severity, and long-term symptoms in low-velocity motor vehicle collisions. Medical Science Monitor. 2005;11(10):RA316-RA321.